
£500m+
Funding arranged
Acquisition mortgages, development and expansion finance, bridging, refinance and multi-park portfolio facilities, arranged around how a trading park actually earns.
✓An initial conversation. No obligation to proceed.
Holiday parks are commercial trading businesses, and they are financed differently from a home or a buy-to-let. The right facility is rarely the cheapest headline rate. It is the one that completes on time, suits a park whose income is concentrated in the season and lets you grow the trade and the holiday-home sales pipeline once it is yours. We arrange that facility. Typical park mortgages run at 50 to 65 per cent loan to value over 15 to 25 year terms.
We work with park operators, investors, multi-park groups and developers across the country. We arrange the acquisition mortgage that buys a static, lodge, touring or glamping park, the development and expansion finance that funds new lodge pitches, glamping or site infrastructure, the bridging that secures a park or an off-market opportunity quickly, the refinance and equity release that moves a park onto better terms or frees capital for the next deal, and the portfolio facilities that hold a group of parks for the long run.
A holiday park is underwritten as a trading business, not on residential loan to value. Lenders read the EBITDA, the pitch-fee and site-fee income, the holiday-home sales margin, the licence and planning position and the operator behind the park. Because we sit across more than one hundred lender relationships, we know which desks genuinely back holiday parks and caravan parks, at what leverage and on what terms. That is the work. We are an arranger and introducer, not a lender, and we do not give financial, legal or tax advice.
Products covering the whole holiday park and caravan park journey, used alone or in sequence.
We arrange commercial mortgages to buy static caravan parks, lodge parks, touring and camping sites and glamping ventures across the UK. As an introducer we place each case with lenders who understand park trading income rather than residential loan to value.
Learn moreWe arrange staged development finance to add new static, lodge, touring and glamping pitches, build facilities and lay infrastructure. Funding is drawn against cost and end value, then refinanced onto a park mortgage once the new income is trading.
Learn moreWe arrange short-term bridging to buy a holiday or caravan park quickly, whether at auction, against a deadline, or before clean accounts are available. Pricing starts indicatively from around 0.75 percent per month, with a clear exit onto a park mortgage or sale.
Learn moreWe arrange holiday park refinance to move existing park debt onto better terms, exit a bridging loan onto a long-term park mortgage, extend the term, or release equity against improved EBITDA. Released funds can pay for expansion, a further acquisition or a partial release across a multi-park portfolio.
Learn moreWhen you run more than one park, separate loans on separate parks rarely serve you well. We arrange a single facility across the group, secured on the portfolio, sized on aggregate trading and built to flex as you buy, sell and refinance.
Learn moreBuilding a luxury lodge park or a glamping site is a development project before it is a trading business. We arrange staged development funding against cost and end value, with drawdowns that track construction and an exit planned from day one.
Learn moreA holiday park is a trading business, not a row of houses. We arrange income and EBITDA-based commercial mortgages on the park as a going concern, sized on the accounts, the licence, the tenure and the strength of the operator behind it.
Learn moreA residential-style mortgage rarely tells the whole story. The site licence, the season, the pitch-fee roll, the holiday-home sales pipeline and the way you own the park all matter to a lender.
We read the park, its trading accounts and EBITDA, the pitch-fee and holiday-home sales income, the business plan and your timescale, and tell you what is fundable and on what terms.
We shortlist the desks most likely to back a holiday park or caravan park at the leverage you need.
We package the deal, run it to the panel and negotiate heads of terms on your behalf.
We manage valuation, any project monitoring and the legals through to completion or first drawdown.
Every park type is underwritten differently. We know which lenders back each one.
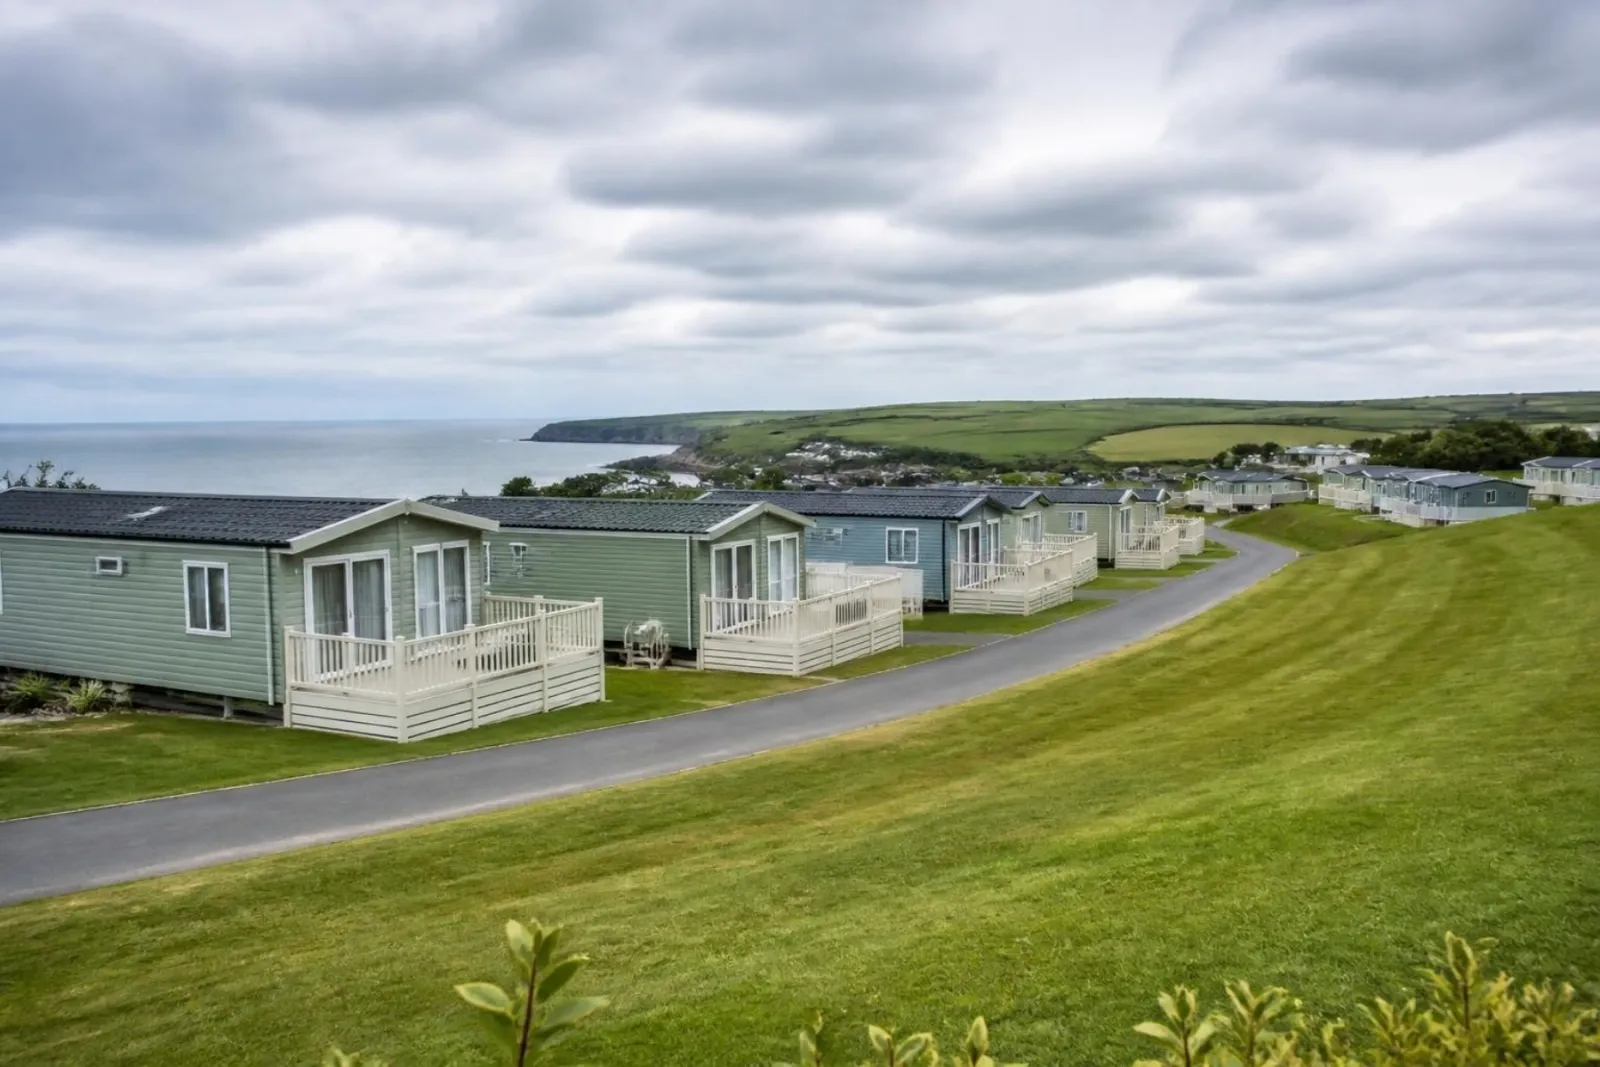
Static caravan and holiday-home parks are commercial trading businesses, and lenders treat them that way. We arrange funding shaped around pitch-fee income, holiday-home sales margin and the strength of your site licence and planning consent.
Learn more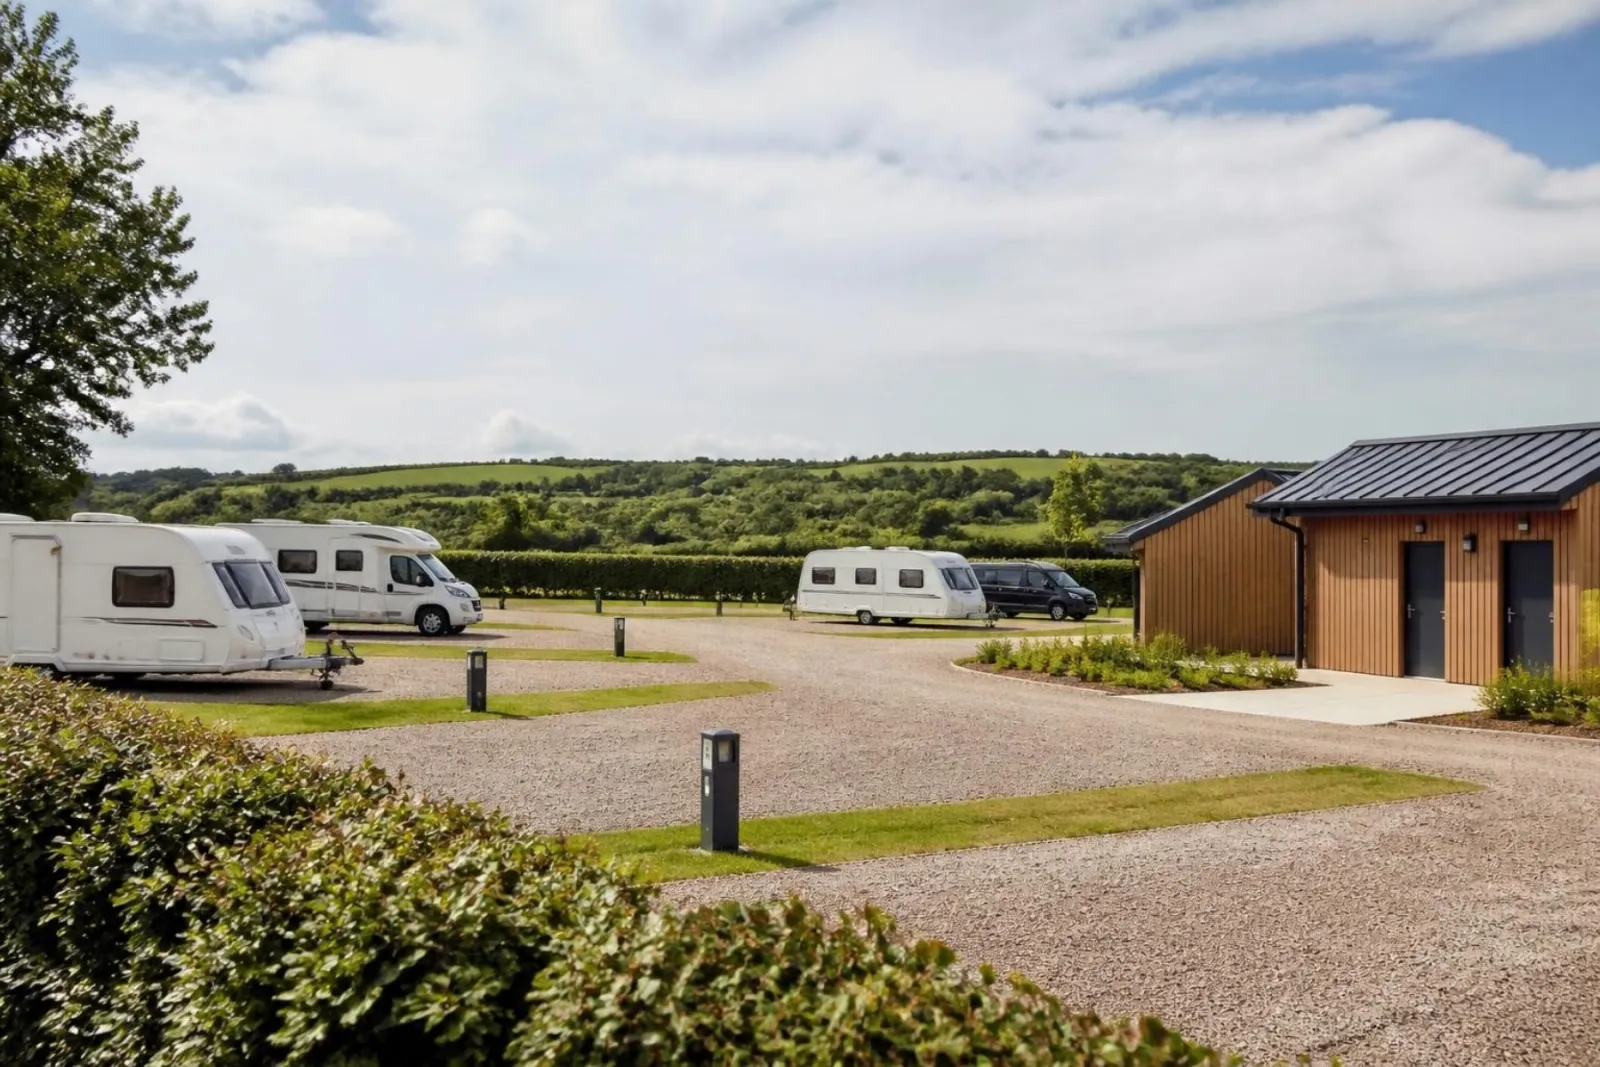
Touring and camping parks are seasonal trading businesses with lighter capital needs than static sites. We arrange commercial funding shaped around nightly and weekly pitch income, facility revenue and any glamping diversification.
Learn more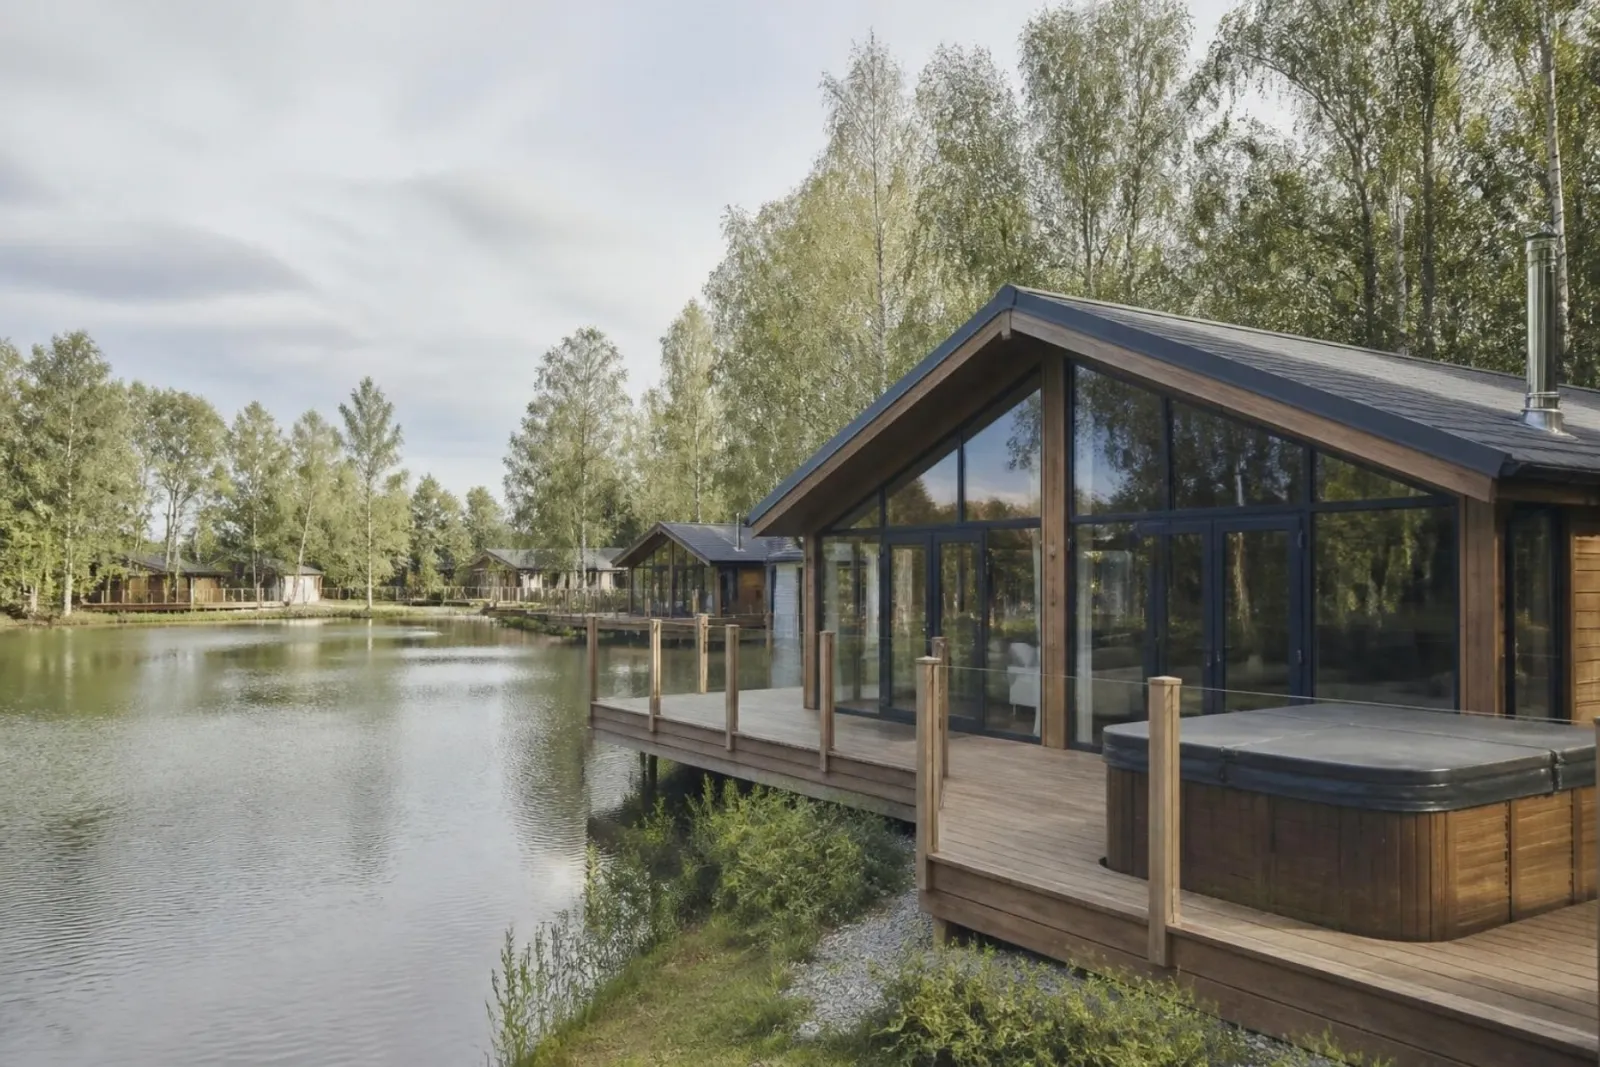
Luxury lodge parks pair high-spec timber lodges with premium locations and per-pitch values above the static average. We arrange commercial funding built around strong sales margin, premium pitch fees and the quality of the consent and tenure.
Learn more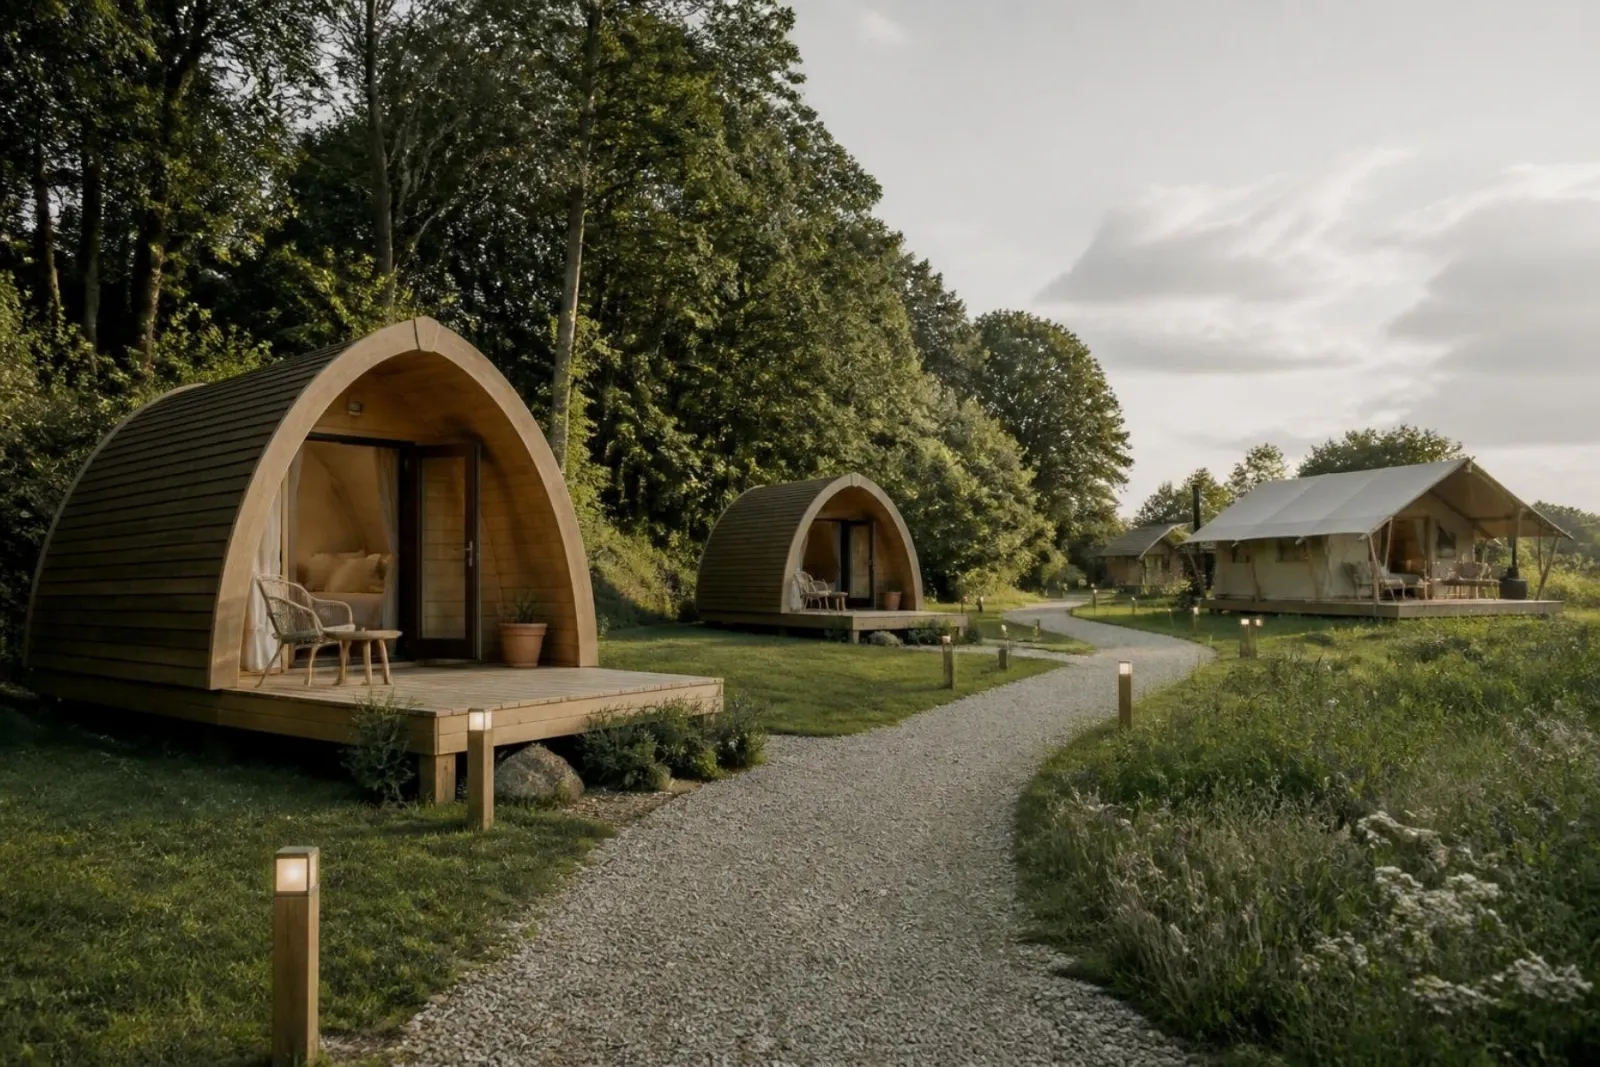
Funding for glamping sites of pods, domes, safari tents and cabins, sized on build cost, end value and the trading income each pitch genuinely earns.
Learn more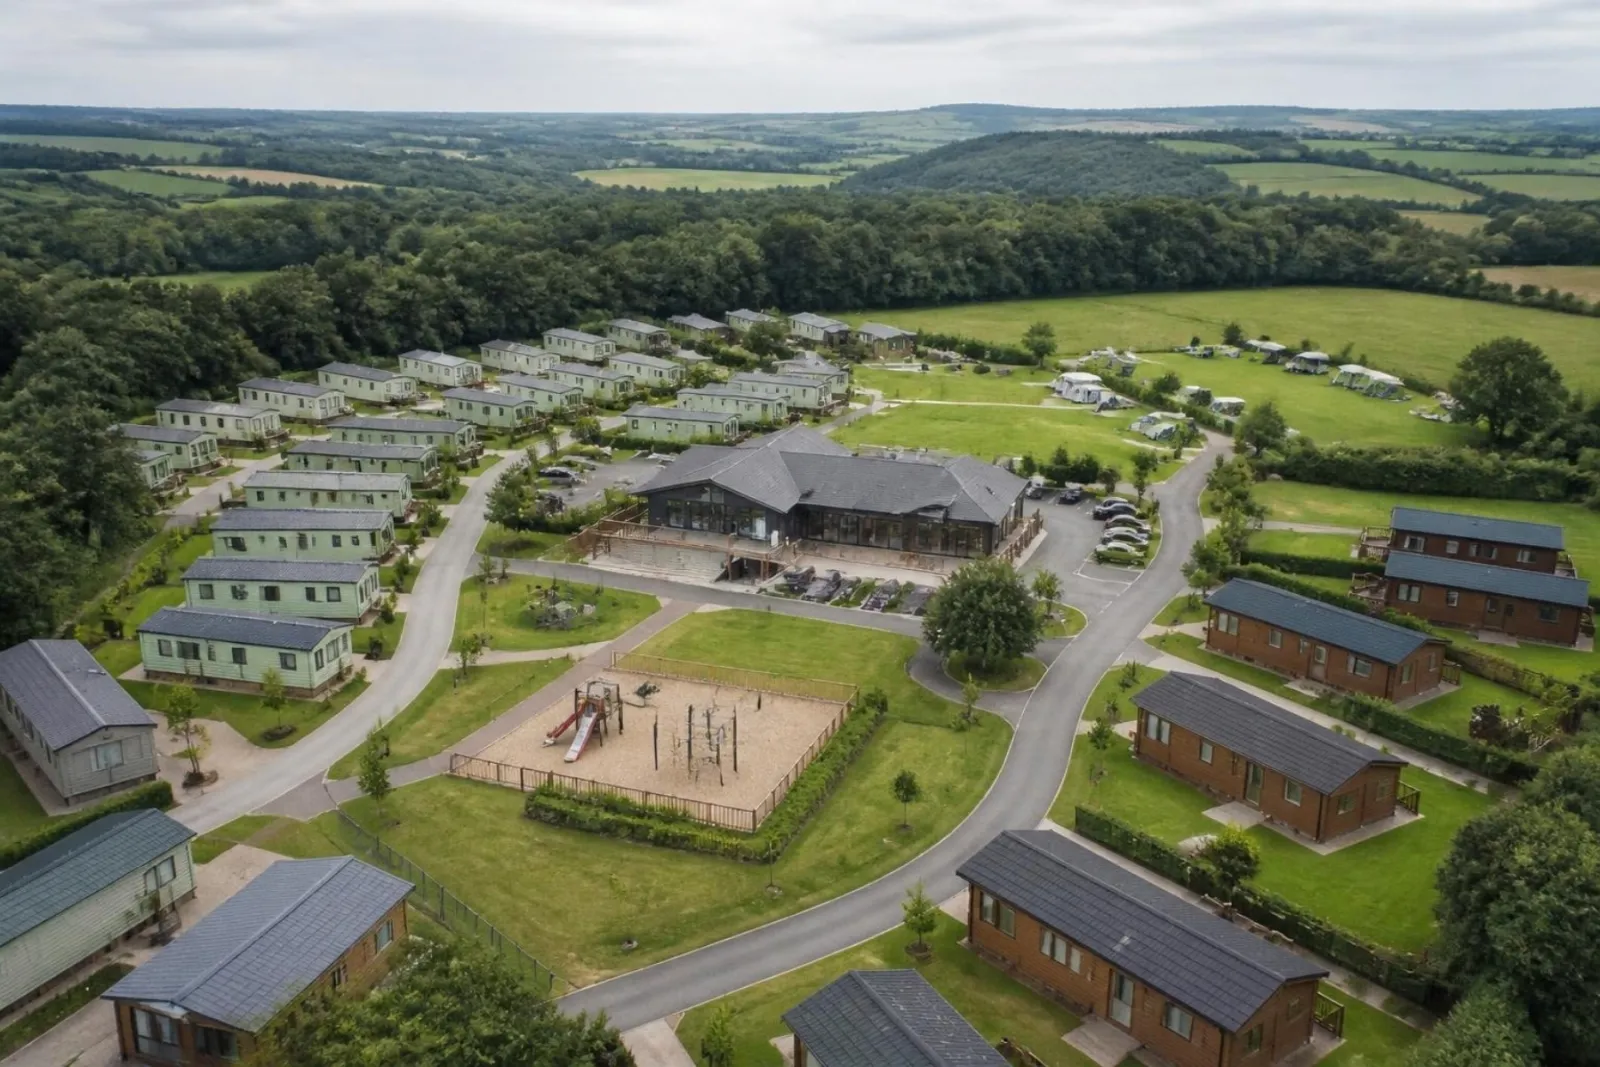
Funding for holiday parks that combine several income streams, sized on the diversified trading earnings the whole operation produces across the season.
Learn more
Funding for parks that combine holiday pitches with residential park homes or a dwelling, where tenure and the holiday-to-residential consent split decide the lending.
Learn moreWe ground every appraisal in published industry research. Figures are indicative national averages and vary widely by park, location and season.
An arranger on the borrower's side, working across the whole of the park finance market.
More than one hundred lender relationships across high-street banks, challenger banks and specialist leisure and holiday park funders.
A holiday park is a commercial trading business, underwritten on EBITDA, pitch-fee and site-fee income and holiday-home sales margin, not residential loan to value. We package deals the way the park finance desks read them.
Acquisition, bridging, development and expansion, refinance, equity release and multi-park portfolio facilities, arranged on their own or in sequence.
An arranger and introducer working for the borrower, not a single lender. We do not give financial, legal or tax advice.
We fund the acquisition or the development, then refinance or release equity once the park is trading and growing. The full journey.
Savills park research, UKCCA sector data and VisitBritain tourism figures frame every appraisal.

“Arranging finance for holiday parks, caravan parks and leisure property is something I have done for over 25 years. Every deal still comes through me personally: the structuring, the packaging, the credit conversations, the legals and the drawdown. Clients are not handed off. They get answers.
Send us the outline and we will come back with a view on fundability and likely terms within one working day.